🏡 Property Capital Gains Tax Calculator (With & Without Indexation)

Work out the capital gains tax on selling a house, flat, plot or building in India — and compare the tax WITH indexation (20%) against WITHOUT indexation (12.5%) side by side.

4.5 out of 5 (4 ratings)

Enter details

Use the higher of the sale price and the stamp-duty (circle-rate) value — see Section 50C.
Include stamp duty, registration and brokerage paid at purchase. If bought before 2001-02, enter its value on 1-Apr-2001 (or actual cost if higher).
Capital improvements only — extensions or major renovation, not routine repairs.
Brokerage, legal and transfer fees paid to sell the property.
Long-term gain you will reinvest to claim an exemption. Leave 0 if none.

Fill in the details and click Calculate to see your results.

Formula at a glance

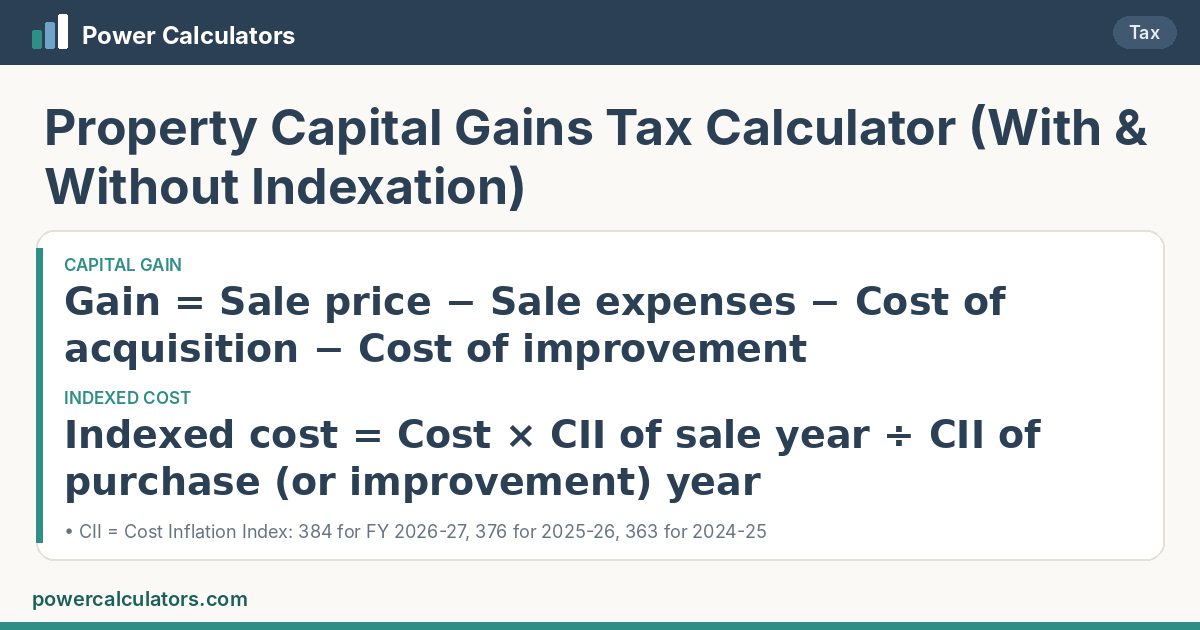
Property Gain Tax formula: Gain = Sale price − Sale expenses − Cost of acquisition − Cost of improvement; Indexed cost = Cost × CII of sale year ÷ CII of purchase (or improvement) year
How the property gain tax works: Gain = Sale price − Sale expenses − Cost of acquisition − Cost of improvement

📱 Also in our Android app

This calculator is also in our free app. Sign in with the same account to keep your history in sync.

  • Financial CalculatorEMI, SIP, PPF, NPS, post office schemes and government-employee calculatorsGet it on Google Play

Rate this calculator

Was it useful? A quick star rating helps others — and you can leave a comment too.
Rate it: ★ ★ ★ ★ ★

📘 About the Property Gain Tax Calculator

Capital gains tax on property is the tax on the profit you make when you sell a house, flat, plot or building in India. This calculator works it out two ways at once, without indexation and with indexation, so you can see which costs you less.

Enter the sale and purchase details, the years, and a few facts about you as a taxpayer. It shows the tax under both methods and the amount you actually owe.

🧮 Formula

Capital gain
Gain = Sale price − Sale expenses − Cost of acquisition − Cost of improvement
Indexed cost
Indexed cost = Cost × CII of sale year ÷ CII of purchase (or improvement) year
Long-term tax without indexation
Tax = 12.5% × Gain
Long-term tax with indexation
Tax = 20% × (Sale price − Sale expenses − Indexed costs)
Short-term tax
Tax = Gain × your slab rate
Add surcharge and cess
Total tax = Tax × (1 + surcharge) × 1.04

Where

  • CII = Cost Inflation Index: 384 for FY 2026-27, 376 for 2025-26, 363 for 2024-25
  • Long-term = property held more than 24 months
  • Surcharge on long-term gains is capped at 15%; cess is 4%

✏️ Worked examples

Bought for ₹40 lakh in FY 2015-16, sold for ₹1.4 crore in FY 2026-27

You enter
Sale Price of Property₹14,000,000
Purchase Price₹4,000,000
Financial Year of Purchase2015-16 (CII 254)
Cost of Improvement (if any)₹0
Year of Improvement (if any)2015-16 (CII 254)
Expenses on Sale₹0
Financial Year of Sale2026-27 (CII 384)
Holding PeriodMore than 24 months (long-term)
Acquired before 23 July 2024?Yes, before 23 July 2024
Taxpayer TypeResident individual / HUF
Exemption Claimed (Sec 54 / 54EC / 54F)₹0
Your Income Tax Slab Rate (short-term gains only)30%
Surcharge ApplicableNone
You get
Capital Gains Tax Payable₹13,00,000
Tax Without Indexation₹13,00,000
Tax With Indexation₹16,54,173.23
Taxable Gain Without Indexation₹1,00,00,000
Taxable Gain With Indexation₹79,52,755.91
Indexed Cost of Acquisition₹60,47,244.09
Indexed Cost of Improvement₹0
Tax Saved by the Better Method₹3,54,173.23
Net Proceeds After Tax₹1,27,00,000

Here the lower tax is without indexation: ₹13,00,000, against ₹16,54,173.23 with indexation. The tax payable is ₹13,00,000.

Bought for ₹25 lakh in FY 2002-03, sold for ₹1 crore in FY 2026-27

You enter
Sale Price of Property₹10,000,000
Purchase Price₹2,500,000
Financial Year of Purchase2002-03 (CII 105)
Cost of Improvement (if any)₹0
Year of Improvement (if any)2015-16 (CII 254)
Expenses on Sale₹0
Financial Year of Sale2026-27 (CII 384)
Holding PeriodMore than 24 months (long-term)
Acquired before 23 July 2024?Yes, before 23 July 2024
Taxpayer TypeResident individual / HUF
Exemption Claimed (Sec 54 / 54EC / 54F)₹0
Your Income Tax Slab Rate (short-term gains only)30%
Surcharge ApplicableNone
You get
Capital Gains Tax Payable₹1,78,285.71
Tax Without Indexation₹9,75,000
Tax With Indexation₹1,78,285.71
Taxable Gain Without Indexation₹75,00,000
Taxable Gain With Indexation₹8,57,142.86
Indexed Cost of Acquisition₹91,42,857.14
Indexed Cost of Improvement₹0
Tax Saved by the Better Method₹7,96,714.29
Net Proceeds After Tax₹98,21,714.29

This time indexation wins by a wide margin: ₹1,78,285.71 against ₹9,75,000. Choosing the better method saves ₹7,96,714.29.

🧭 How to use this calculator

What you enter

  • Sale Price of Property (₹)Use the higher of the sale price and the stamp-duty (circle-rate) value — see Section 50C.
  • Purchase Price (₹)Include stamp duty, registration and brokerage paid at purchase. If bought before 2001-02, enter its value on 1-Apr-2001 (or actual cost if higher).
  • Financial Year of Purchase
  • Cost of Improvement (if any) (₹)Capital improvements only — extensions or major renovation, not routine repairs.
  • Year of Improvement (if any)
  • Expenses on Sale (₹)Brokerage, legal and transfer fees paid to sell the property.
  • Financial Year of Sale
  • Holding Period
  • Acquired before 23 July 2024?
  • Taxpayer Type
  • Exemption Claimed (Sec 54 / 54EC / 54F) (₹)Long-term gain you will reinvest to claim an exemption. Leave 0 if none.
  • Your Income Tax Slab Rate (short-term gains only)
  • Surcharge Applicable

What you get

  • Capital Gains Tax Payable
  • Tax Without Indexation
  • Tax With Indexation
  • Taxable Gain Without Indexation
  • Taxable Gain With Indexation
  • Indexed Cost of Acquisition
  • Indexed Cost of Improvement
  • Tax Saved by the Better Method
  • Net Proceeds After Tax

💡 Who can choose indexation?

Only resident individuals and HUFs, and only for land or buildings bought before 23 July 2024 and sold on or after that date. They pay the lower of the two taxes.

NRIs, companies, firms, and anyone who bought on or after 23 July 2024 pay 12.5% without indexation. If indexation is not open to you, the 'with indexation' figure is shown for comparison only and the tax payable follows the without-indexation method.

💡 Reducing the tax

Long-term gains can be exempt when reinvested: Section 54 (buying or building another house, capped at ₹10 crore), Section 54EC (specified bonds, up to ₹50 lakh) or Section 54F (when the property sold is land or a commercial property rather than a house). From 1 April 2026 these provisions carry new section numbers under the Income-tax Act, 2025, but the rules are unchanged.

💡 Good to know

  • Include stamp duty, registration and brokerage paid at purchase in the purchase price. Only capital improvements count as improvement cost.
  • If the stamp-duty (circle-rate) value is higher than the sale price beyond the permitted tolerance, tax is generally worked out on the stamp-duty value. Enter that value as the sale price.
  • For property bought before 1 April 2001, use its fair market value on 1 April 2001, or the actual cost if higher.
  • If the result is a loss, the tax is nil. Loss set-off, basic-exemption adjustment, TDS and interest are not included.
  • This is an estimate for planning, not tax advice. Check the final figures with a chartered accountant.

❓ Frequently asked questions

What is the holding period for long-term gains on property?

More than 24 months. Property sold within 24 months gives short-term gains taxed at your slab rate.

Is indexation still available?

Only as a choice for resident individuals and HUFs on property acquired before 23 July 2024. Everyone else pays 12.5% without indexation.

Can I avoid the tax by reinvesting?

You can claim an exemption under Section 54, 54EC or 54F if you meet the conditions and time limits. Enter the amount you will reinvest.

How is capital gain on sale of property calculated?

Sale price minus sale expenses minus purchase cost (indexed, if you choose the 20% option for property bought before 23 July 2024) minus improvement cost. Tax is 12.5% without indexation or 20% with indexation, plus cess.

What is the cost inflation index for 2026-27?

The calculator's list includes the CII notified for each year; FY 2001-02 is the base year (100).

What people are saying
★★★★★
Anonymous · 11 Oct 2026
★★★☆☆
Anonymous · 05 Oct 2026
★★★★★
Anonymous · 29 Sep 2026
★★★★★
Anonymous · 28 Sep 2026