🎯 Debt Payoff Calculator: Snowball vs Avalanche

Got several debts? Find the fastest and cheapest way to become debt-free.

No ratings yet — be the first

Enter details

Log in or create a free account to save your inputs and results, so you don't have to enter them again next time.🔒 No spam, ever. We never sell or share your details, and you can delete your history or account at any time. Privacy policy

Fill in the details and click Calculate to see your results.

Formula at a glance

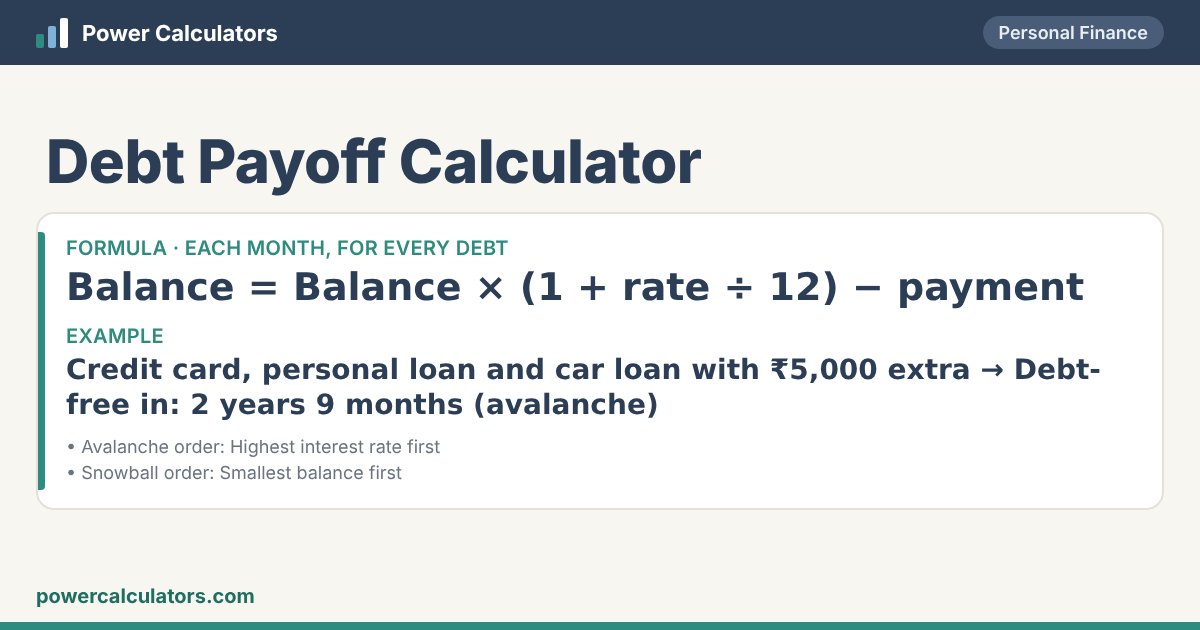
Debt Payoff Calculator: Each month, for every debt — Balance = Balance × (1 + rate ÷ 12) − payment. Example: Credit card, personal loan and car loan with ₹5,000 extra → Debt-free in: 2 years 9 months (avalanche)
How the Debt Payoff Calculator works: Each month, for every debt — Balance = Balance × (1 + rate ÷ 12) − payment

📱 Also in our Android app

This calculator is also in our free app. Sign in with the same account to keep your history in sync.

  • Financial CalculatorEMI, SIP, PPF, NPS, post office schemes and government-employee calculatorsGet it on Google Play

Rate this calculator

Was it useful? A quick star rating helps others — and you can leave a comment too.
Rate it: ★ ★ ★ ★ ★

📘 About the Debt Payoff Calculator

The debt avalanche pays the minimum on every debt and puts every extra rupee on the one with the highest interest rate — mathematically the cheapest. The debt snowball attacks the smallest balance first, giving quick wins that keep many people motivated. When a debt is cleared, its payment rolls on to the next.

Enter each debt's balance, interest rate and monthly payment, plus any extra you can pay. The calculator runs both plans month by month and shows when you will be debt-free, the interest you will pay and when each debt is cleared.

🧮 Formula

Each month, for every debt
Balance = Balance × (1 + rate ÷ 12) − payment
Avalanche order
Highest interest rate first
Snowball order
Smallest balance first

✏️ Worked examples

Credit card, personal loan and car loan with ₹5,000 extra

You enter
Currency₹ Indian rupee
Debt 1 nameCredit card
Debt 1 balance80000
Debt 1 interest rate42%
Debt 1 monthly payment4000
Debt 2 namePersonal loan
Debt 2 balance300000
Debt 2 interest rate14%
Debt 2 monthly payment9000
Debt 3 nameCar loan
Debt 3 balance400000
Debt 3 interest rate9.5%
Debt 3 monthly payment10000
Extra you can pay each month5000
You get
Debt-free in2 years 9 months (avalanche)
Debt-free dateAugust 2029
Total debt now₹7,80,000 (7.8 lakh)
Interest — avalanche₹1,43,309
Interest — snowball₹1,43,309 (2 years 9 months)
Cheapest methodAvalanche (highest interest first)
Your extra ₹5,000 a month saves₹79,310 and 11 months

Debt-free in 2 years 9 months (avalanche); interest ₹1,43,309.

Two credit cards, no extra

You enter
Currency₹ Indian rupee
Debt 1 nameCard A
Debt 1 balance60000
Debt 1 interest rate40%
Debt 1 monthly payment3000
Debt 2 nameCard B
Debt 2 balance25000
Debt 2 interest rate36%
Debt 2 monthly payment1500
Extra you can pay each month0
You get
Debt-free in2 years 6 months (avalanche)
Debt-free dateMay 2029
Total debt now₹85,000
Interest — avalanche₹48,988
Interest — snowball₹48,988 (2 years 6 months)
Cheapest methodSnowball (smallest balance first)

2 years 6 months (avalanche).

🧭 How to use this calculator

What you enter

  • Currency
  • Debt 1 name
  • Debt 1 balance
  • Debt 1 interest rate (%)
  • Debt 1 monthly payment
  • Debt 2 name
  • Debt 2 balance
  • Debt 2 interest rate (%)
  • Debt 2 monthly payment
  • Debt 3 name
  • Debt 3 balance
  • Debt 3 interest rate (%)
  • Debt 3 monthly payment
  • Debt 4 name
  • Debt 4 balance
  • Debt 4 interest rate (%)
  • Debt 4 monthly payment
  • Debt 5 name
  • Debt 5 balance
  • Debt 5 interest rate (%)
  • Debt 5 monthly payment
  • Extra you can pay each month

What you get

  • Debt-free in
  • Debt-free date
  • Total debt now
  • Interest — avalanche
  • Interest — snowball
  • Cheapest method
  • Your extra ₹5,000 a month saves

💡 Get out of debt faster

  • Stop adding new card spending while you repay.
  • Ask your bank for a lower rate or a balance transfer.
  • Put bonuses and tax refunds straight onto the top-priority debt.
  • Keep a small emergency fund so a surprise bill does not go on the card.

❓ Frequently asked questions

Which is better, debt snowball or avalanche?

The avalanche always costs the least interest. The snowball can cost a little more but clears accounts sooner, which helps some people stick to the plan. If the difference is small, choose the one you will follow.

Should I pay off credit card debt first?

Almost always: Indian credit cards charge 36–45% a year. Even a personal loan to clear card dues can save money if you stop using the card.

Should I invest or pay off debt?

Clear any debt costing more than you can safely earn — credit cards and personal loans first. Low-rate home loans can run alongside investing.

What if my minimum payment does not cover the interest?

The debt will grow forever. The calculator warns you; pay more or talk to the lender about restructuring.