🏧 SWP Calculator

Plan a systematic withdrawal plan (SWP): see the balance left, total withdrawn, how many years your corpus lasts, the withdrawal that lasts exactly your term and an inflation step-up option.

3.5 out of 5 (2 ratings)

Enter details

Log in or create a free account to save your inputs and results, so you don't have to enter them again next time.🔒 No spam, ever. We never sell or share your details, and you can delete your history or account at any time. Privacy policy

Fill in the details and click Calculate to see your results.

Formula at a glance

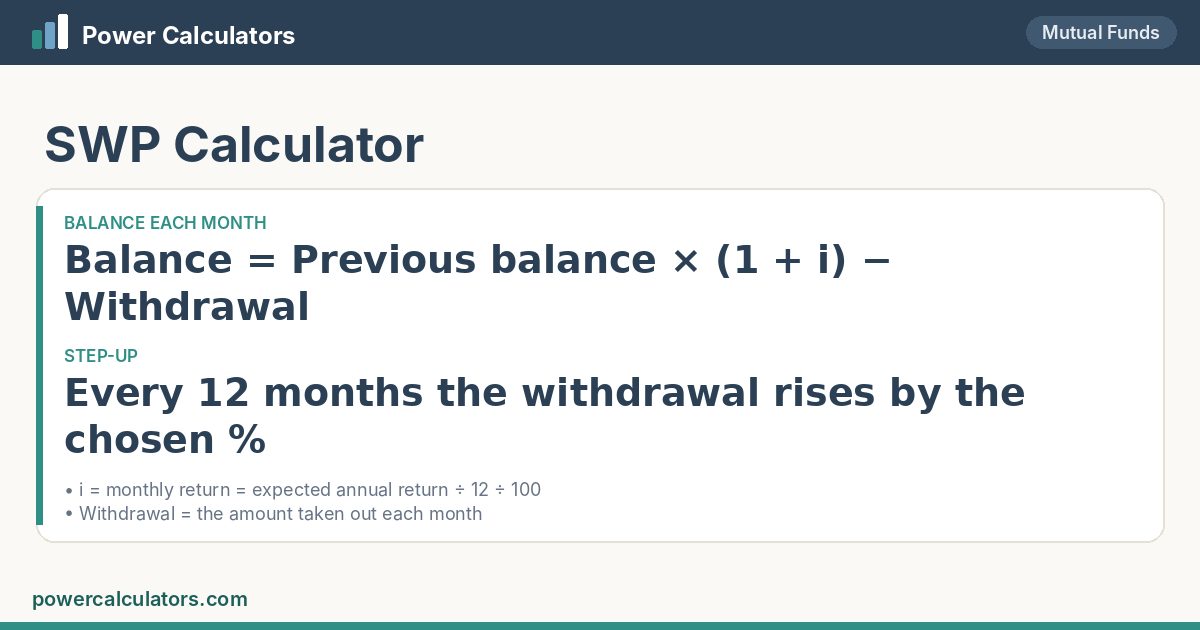
SWP Calculator formula: Balance = Previous balance × (1 + i) − Withdrawal; Every 12 months the withdrawal rises by the chosen %
How the swp calculator works: Balance = Previous balance × (1 + i) − Withdrawal

📱 Also in our Android app

This calculator is also in our free app. Sign in with the same account to keep your history in sync.

  • Financial CalculatorEMI, SIP, PPF, NPS, post office schemes and government-employee calculatorsGet it on Google Play

Rate this calculator

Was it useful? A quick star rating helps others — and you can leave a comment too.
Rate it: ★ ★ ★ ★ ★

📘 About the SWP Calculator

A systematic withdrawal plan (SWP) lets you take a fixed amount from your mutual fund every month while the rest stays invested. It is a popular way to turn a lump sum — a retirement corpus, gratuity or bonus — into a regular income.

Enter the corpus, the monthly withdrawal, the expected return and the term. The calculator tracks your balance month by month, shows how long the money lasts, the withdrawal that uses it up exactly over your term, and the amount you can take without touching the capital. Use the annual step-up to raise the withdrawal with inflation.

🧮 Formula

Balance each month
Balance = Previous balance × (1 + i) − Withdrawal
Step-up
Every 12 months the withdrawal rises by the chosen %

Where

  • i = monthly return = expected annual return ÷ 12 ÷ 100
  • Withdrawal = the amount taken out each month
If withdrawals are larger than the returns, the balance falls and can reach zero before the end of the period.

✏️ Worked examples

₹50 lakh corpus, ₹30,000 a month for 20 years at 8%

You enter
Starting Corpus₹5,000,000
Monthly Withdrawal₹30,000
Annual Withdrawal Step-up0%
Expected Annual Return8%
Term20 yrs
You get
Remaining Balance₹69,63,401
Total Withdrawn₹72,00,000
Net Returns Earned₹91,63,401
Corpus LastsMore than 100 years — the corpus keeps growing
Withdrawal Rate7.20% of the corpus a year
Monthly Withdrawal That Uses the Corpus Exactly in 20 Years₹41,822
Monthly Withdrawal That Never Touches the Capital₹33,333

Balance after 20 years ₹69,63,401; corpus lasts More than 100 years — the corpus keeps growing.

₹1 crore, ₹60,000 a month rising 5% a year

You enter
Starting Corpus₹10,000,000
Monthly Withdrawal₹60,000
Annual Withdrawal Step-up5%
Expected Annual Return9%
Term25 yrs
You get
Remaining Balance₹0
Total Withdrawn₹2,65,93,478
Net Returns Earned₹1,65,93,478
Corpus Lasts21 years 6 months
Withdrawal Rate7.20% of the corpus a year
Monthly Withdrawal That Uses the Corpus Exactly in 25 Years₹83,920
Monthly Withdrawal That Never Touches the Capital₹75,000

Corpus lasts 21 years 6 months.

₹20 lakh, ₹20,000 a month for 10 years

You enter
Starting Corpus₹2,000,000
Monthly Withdrawal₹20,000
Annual Withdrawal Step-up0%
Expected Annual Return7%
Term10 yrs
You get
Remaining Balance₹5,57,627
Total Withdrawn₹24,00,000
Net Returns Earned₹9,57,627
Corpus Lasts12 years 7 months
Withdrawal Rate12.00% of the corpus a year
Monthly Withdrawal That Uses the Corpus Exactly in 10 Years₹23,222
Monthly Withdrawal That Never Touches the Capital₹11,667

Balance ₹5,57,627.

₹50 lakh, ₹30,000 a month for 10 years at 8%

You enter
Lump sum invested₹5,000,000
Monthly withdrawal₹30,000
Expected return8% a year
Period10 years
You get
Balance at the end₹5,609,820.12
Total withdrawn₹3,600,000.00
Total returns₹4,209,820.12

After ten years of withdrawals of ₹30,000, a substantial balance is still invested.

💡 How SWP works

  • Each month the fund earns returns on the remaining balance.
  • Your withdrawal is paid out by redeeming units.
  • If the return is higher than the withdrawal rate, the balance keeps growing.
  • Only the gains in each withdrawal are taxed, which makes SWP tax-efficient.

💡 Safe withdrawal guide

  • 4% a year of the corpus lasts 30+ years in most market histories.
  • 6% a year lasts about 20–25 years at 8% returns.
  • 8% or more a year will usually run out within 15–20 years.

❓ Frequently asked questions

How much can I withdraw safely?

A withdrawal close to the expected return protects your capital. Withdrawing much more than the return steadily uses up the principal.

Is SWP taxable?

Each withdrawal is treated as a redemption, so it may trigger capital gains tax on the gain portion.

SWP or dividend option?

SWP gives you control over the amount and timing, while dividends are irregular and not guaranteed.

What is SWP?

A systematic withdrawal plan: a fixed monthly redemption from a mutual fund, giving you a regular income while the rest stays invested.

How is SWP calculated?

Each month: new balance = old balance × (1 + monthly return) − withdrawal. The calculator repeats this for every month of your term.

Can I add inflation to SWP?

Yes — set the annual step-up to the inflation rate (say 6%) and the withdrawal rises each year.

Which is the best fund for SWP?

Balanced advantage, hybrid or debt funds are common for SWP because they swing less than pure equity funds.

What people are saying
★★☆☆☆
Anonymous · 05 Oct 2026
★★★★★
Anonymous · 04 Oct 2026